A loan officer website that turns a referral into an application
A loan officer website earns its keep when a borrower who was given your name can find you, read the program they were told about, run an estimate and start your application, all from a phone, without calling first.
What usually goes wrong for loan officers
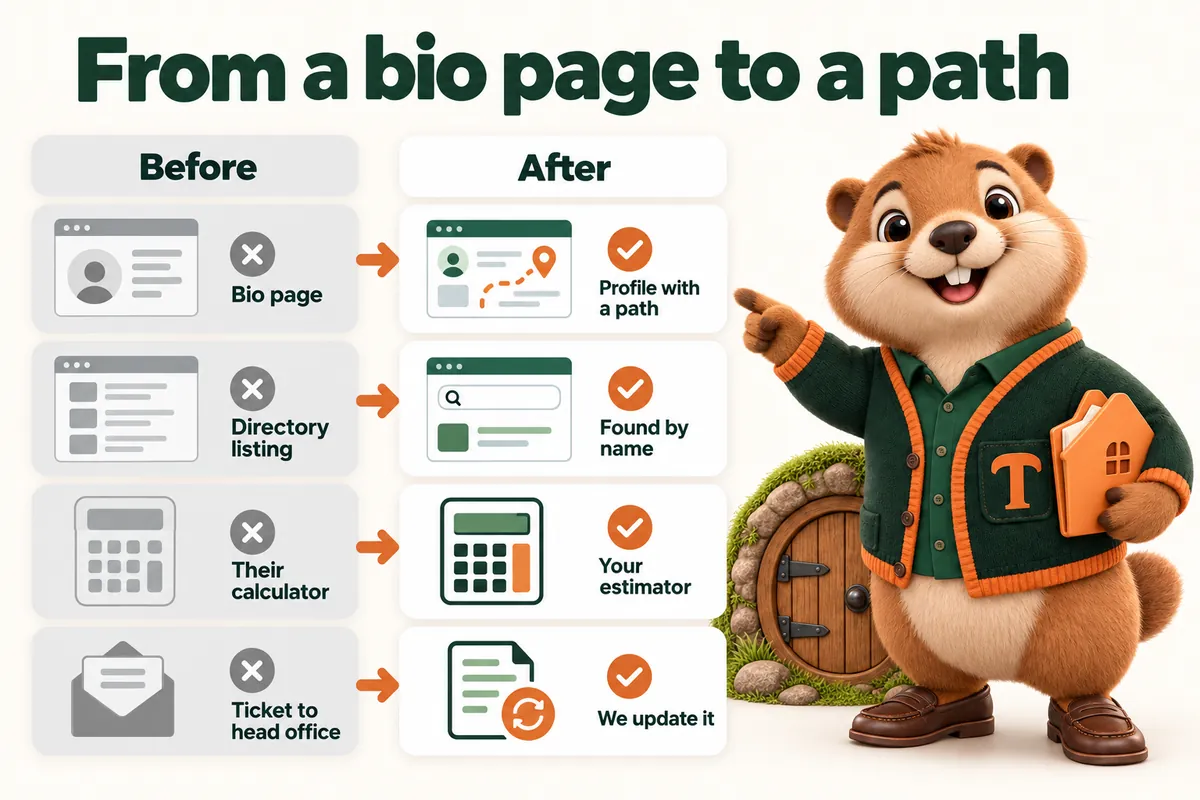
- The corporate template page has your photo and a phone number and nothing a borrower can act on.
- Referrals from agents search your name and land on a directory listing instead of on you.
- Every calculator on the market sends the borrower to someone else's lead form.
- You cannot change a word on your page without opening a ticket with head office.
The pages your site will carry
8 pages at launch, each with the same disclosure block, identifiers and application path.
- Home
- About you, with NMLS identifier and licensed states
- One page per loan program you originate
- Payment estimator
- How the application works
- For real estate agents
- Reviews and testimonials
- Contact and apply
Payment estimator for purchase and refinance
Configured with purchase price, down payment, term and the rate you choose to publish, if any. It shows an illustrative principal and interest figure, labeled as an estimate and not a quote, offer or pre-approval, and sends the borrower's name, contact details and inputs into your CRM or LOS as a lead.
Every figure the estimator shows is illustrative. It is never a quote, an offer, a rate lock, an approval or a statement of eligibility. The wording and the disclosures are approved by your compliance team before launch.
What clients say the site changed
“They asked to see the questions customers genuinely ask us about home loan consultations, which I respected. The recurring questions were pulled out, rewritten clearly, and approved line by line by our team. New starters read it too; it has become our reference, not just the customers'.”
What they got: FAQ research and editorial review for home loan consultations
“The preparation page for home loan consultations works because it keeps its focus. It explains what the first conversation needs, and deliberately asks for nothing sensitive online. The link now goes out with our reply to every new inquiry.”
What they got: Preparation guide and inquiry support for home loan consultations
“Getting the home loan consultations wording right mattered more to us than any visual choice. It explains what an inquiry achieves and is honest about what still needs a proper discussion. We no longer open every call by correcting the website.”
What they got: Service scope and expectations for home loan consultations
Related case studies
Client projects closest to this kind of mortgage business, with what we built and how long it took.
- A clearer first reply for home loan consultationsDay to day with home loan consultations, replies now start from substance rather than from questions.
- Bringing home loan consultations to the small screenWhen it comes to home loan consultations, the mobile path now ends where it should: at an inquiry.
- No more silence after home loan consultations submissionsWith home loan consultations, the sender leaves knowing the message arrived and what happens next.
Questions from loan officers
Every question, groupedCan I have my own site if I work for a lender?
Usually, yes, subject to your employer's marketing and compliance policy. Many lenders allow originator-owned sites that carry the required identifiers and approved disclosures. We build to whatever your compliance team specifies and hold launch until they have signed off on the disclosure block.
Does the site show rates?
Only if you decide it should, and then only the wording and the disclosures your compliance team supplies. By default the site describes programs and shows an estimator with a rate field you control. We never publish a rate on your behalf.
Where do applications go?
Into the application your LOS or point-of-sale vendor already hosts. The site's apply links carry your originator identifier and the program into that application wherever the vendor supports it, so the borrower lands in your file, not a general queue.
What if I move to another lender?
The domain is yours and the site is yours to keep on the plan. We update your identifiers, licensing lines and disclosures to the new lender's requirements as revisions, and the site continues. Your program pages and articles come with you.
How long until I can send the link to an agent?
Within the launch window on the Solo Originator plan, counted from the onboarding call, and you see the site on a private review link before it is public. The build fee is invoiced only after it is live and you have approved it. Most originators send the first link to their three closest agents the same afternoon it goes live.
What do I actually have to do each month?
Nothing, unless something changes. When it does, you email it or raise it in your client portal: a new licensed state, a program you have stopped originating, a new headshot, a compliance wording change. We make it within the stated turnaround. You never log in to the website itself.
Will this work if most of my business comes from repeat clients?
Yes, and the pages you will care about are different. Repeat and referral traffic arrives knowing your name, so the originator profile and the program pages do the work rather than the search pages. The estimator still earns its place, because a past client checking whether a move makes sense will run the numbers somewhere, and it may as well be on your domain.
What happens to my site if I take a long leave?
It carries on. The hosting, the certificate, the backups and the weekly updates are ours, so nothing lapses while you are away. If you want the site to say you are not taking new applications for a period, that is a revision and we can put it up and take it down on dates you give us.
See it built for loan officers
A live walk-through, on your screen, of the site you would get. Then you know the plan, the launch date and what we need from you.
Book a demo